How Does a Home Appraisal Work? A Complete Guide for Buyers and Sellers
Local Guide Sankari Subburaman October 27, 2026
Local Guide Sankari Subburaman October 27, 2026
A couple in Kirkland have an accepted offer, a mortgage pre-approval and boxes half-packed in the garage. Then the lender’s email arrives. The appraisal came in lower than the agreed price, and the loan will not cover the difference. Suddenly the closing date is in doubt, and nobody is sure what happens next. Appraisals sit quietly in the background of most home sales, then become the centre of attention when numbers do not match.
This guide explains what an appraisal is, who orders it, what the appraiser looks at, how the value is reached, how long it takes, what to do if the figure is low and how buyers and sellers can prepare. If you are buying or selling on the Eastside, speaking with a real estate agent Kirkland WA early helps you understand how local values are likely to hold up.
A home appraisal is an independent, professional opinion of a property’s market value. It is carried out by a licensed or certified appraiser who has no stake in whether the sale goes ahead.
The main reason it exists is to protect the lender. A mortgage is secured by the home, so the bank wants to be sure the property is worth at least as much as the loan. If a buyer defaults, the lender needs to recover its money by selling the house. The appraisal gives them that comfort.
It is worth separating this from the price you agreed. The contract price reflects what a buyer was willing to pay and a seller was willing to accept. The appraised value reflects what comparable homes have recently sold for. Most of the time the two are close. When they are not, the gap needs to be dealt with.
In a typical financed purchase, the lender orders the appraisal, usually through an appraisal management company so that the buyer and agents cannot influence the appraiser. The buyer normally pays the fee, often at the start of the loan process or at closing, and it commonly runs to several hundred dollars depending on the property and location.
Buyers paying cash may skip an appraisal, though some still order one for peace of mind. Sellers sometimes commission a pre-listing appraisal to help set a price, although a lender will still require its own for a buyer’s mortgage. Refinancing, home equity loans and estate settlements also use appraisals.
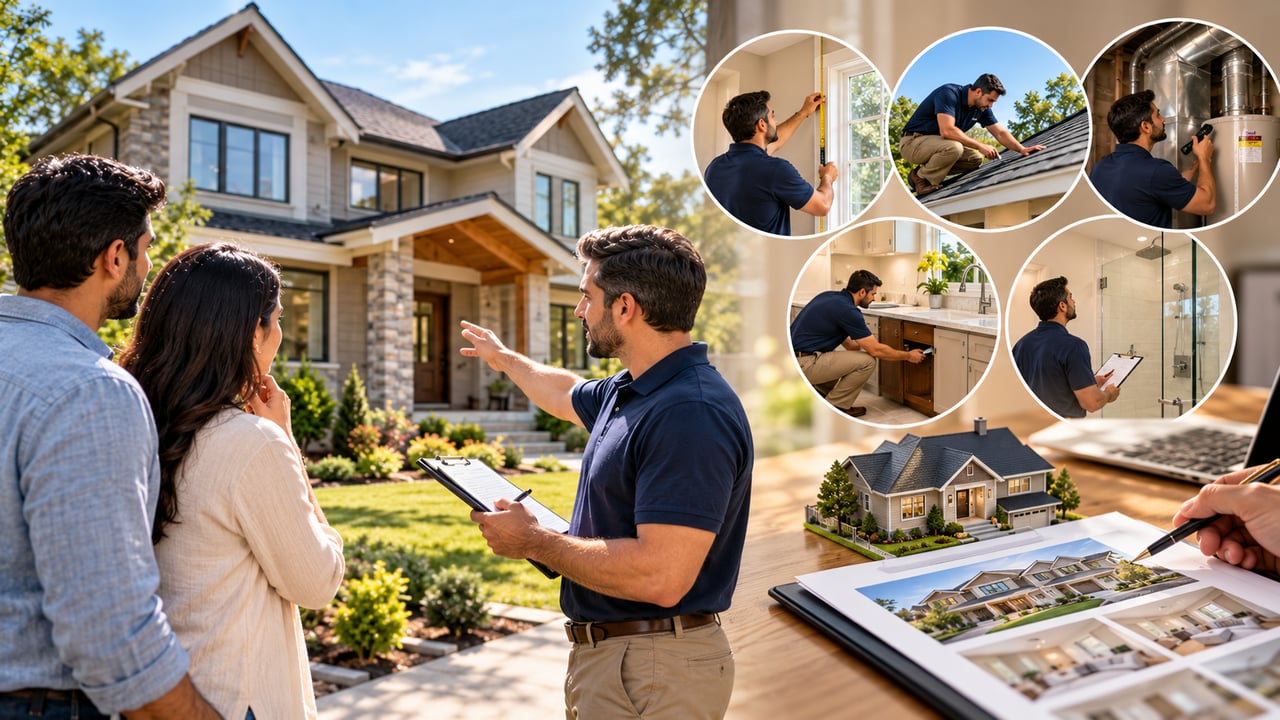
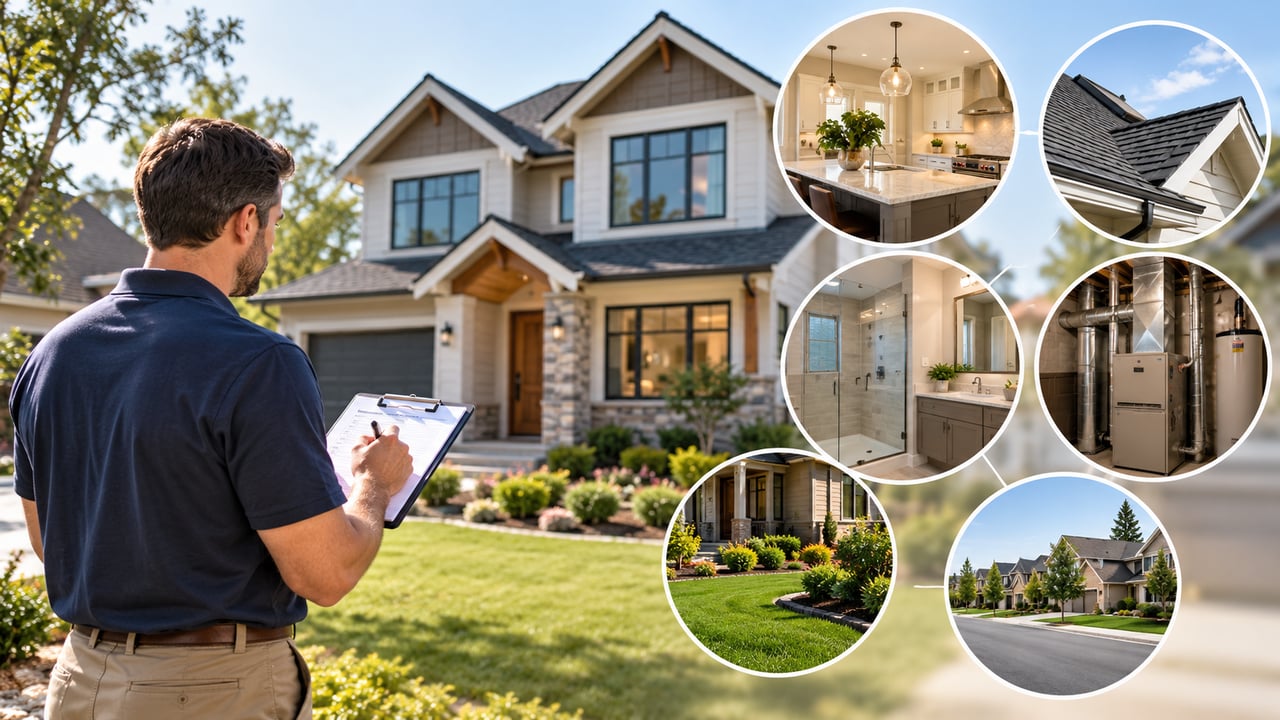
The appraiser visits the property, usually for thirty minutes to an hour, measuring rooms, taking photographs and noting the condition of the home. They record the square footage, the number of bedrooms and bathrooms, the layout, the age and the quality of construction.
Inside, they look at the kitchen, bathrooms, flooring, windows, heating and cooling systems and signs of wear or damage. Outside, they check the roof, siding, foundation, lot size, landscaping, garage and any additions or outbuildings. They also note permitted versus unpermitted work, because finished space without permits may not be counted in the same way.
Location carries a great deal of weight. The appraiser considers the street, the neighbourhood, school districts, nearby amenities, traffic, views and any features that raise or lower demand. Two similar homes can have different values simply because of where they sit.
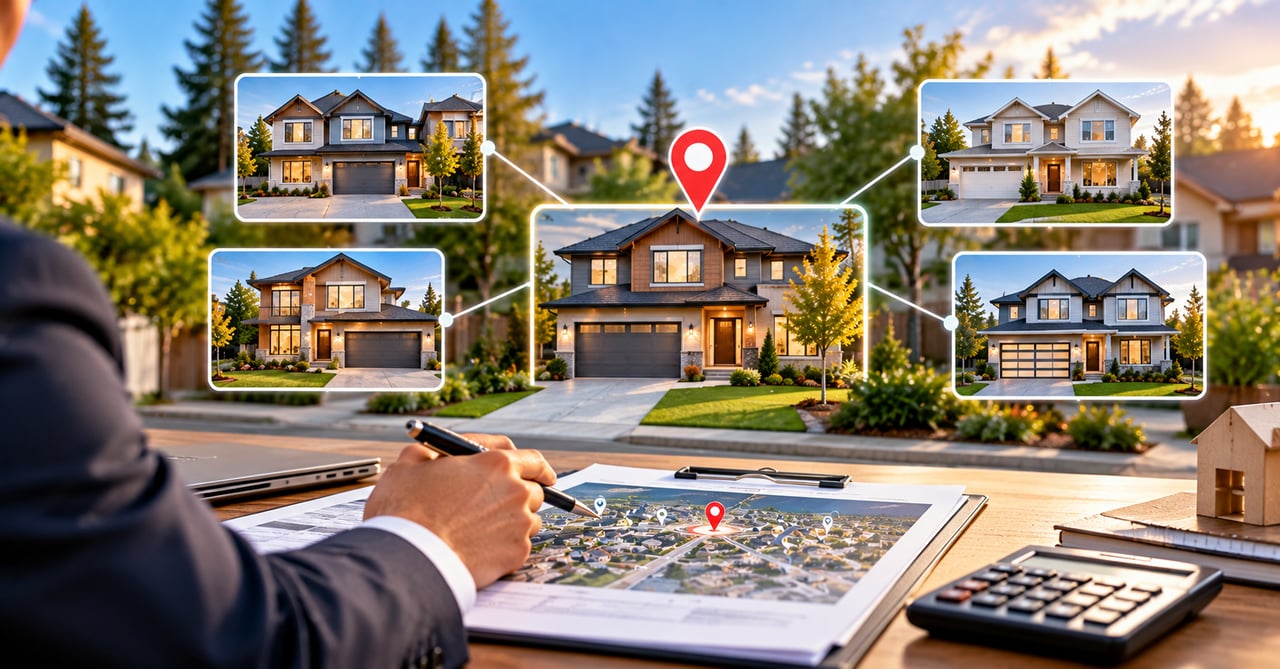
The most common method for a single-family home is the sales comparison approach. The appraiser selects recently sold homes that are similar in size, age, condition and location, often within the past few months and a short distance away. These are called comparables, or comps.
Because no two homes are identical, the appraiser makes adjustments. If a comparable has an extra bathroom, the value of that bathroom is subtracted to match your home. If yours has a renovated kitchen and the comp does not, an amount is added. After adjusting several comps, the appraiser reaches an opinion of value.
Other methods exist. The cost approach estimates what it would cost to rebuild the home, and is more useful for new or unusual properties. The income approach looks at rental income and applies to investment properties. For most homes, the sales comparison approach carries the greatest weight, and the findings are set out in a written report.
The process moves in a fairly predictable order. After the offer is accepted and the loan application begins, the lender orders the appraisal. Then, the appraiser contacts the listing agent or seller to schedule a time to visit the home, which can be done within days. Once the inspection is completed, the appraiser reviews the comps, then writes the report.This can take anywhere from a few days to a few weeks depending on market activity and the complexity of the property.
Delays occur, particularly in peak seasons or locations with few comparable sales. Buyers and agents should keep the closing timeline in mind and ask for updates if the report is slow to arrive.
A low appraisal feels alarming, but there are options, and the right one depends on the contract and the market.
Sellers should remember that the next buyer’s lender will also order an appraisal, so a low figure can reappear if the deal collapses.
Sellers cannot control the appraisal, but good preparation helps the home show at its best. Clean the house, clear clutter and make sure every room is easy to access, including the attic, garage and utility areas. Visible neglect can depress the assessed condition so fix minor problems like dripping taps, cracked fittings and peeling paint.
Prepare a list of improvements with approximate dates and costs, such as a new roof, a remodelled bathroom or upgraded windows. Keep permits and receipts handy. If you know of recent comparable sales that support your price, share them with your agent so they can pass them on if needed.
Buyers should be ready for the possibility of a gap. Check how much cash you have available beyond the down payment, and discuss with your agent whether an appraisal contingency or gap clause makes sense in your offer. In a competitive market, some buyers waive contingencies, but that increases risk, so it deserves careful thought.
Keep in touch with your lender and agent during the appraisal, and be prepared to provide documents quickly. Remember that an appraisal is not an inspection. It estimates value, not hidden defects, so a separate home inspection remains important.
Sankari Realty works with buyers and sellers across the Seattle area and the Eastside, helping clients understand local pricing, prepare homes for sale and respond when numbers do not line up. Its agents guide clients through each stage, from offer to closing.
A local agent who tracks recent sales can anticipate how an appraiser is likely to view a property. They can also supply comparable data, explain adjustments and push back respectfully if a report appears to miss something important.
An appraisal is just one step in a sale, and it is far less stressful when you know what it measures and how to respond. Do the preparation, understand the options and keep communication open. Whether you are buying your first home or selling your fifth, local knowledge makes the process smoother. If you are considering a move across the lake, a realtor in Seattle can help you compare neighbourhoods and plan with realistic numbers.
Stay up to date on the latest real estate trends.
Local Guide
Local Guide
Local Guide
Local Guide
Local Guide
Local Guide
Local Guide
Local Guide
Local Guide